Understanding Negative Liability in GSTR-3B (with Illustration)
The GST portal now allows negative tax liability in GSTR-3B in cases where credit notes are issued. However, the manner of utilisation needs to be clearly understood to avoid errors.
🔍 What does this mean?
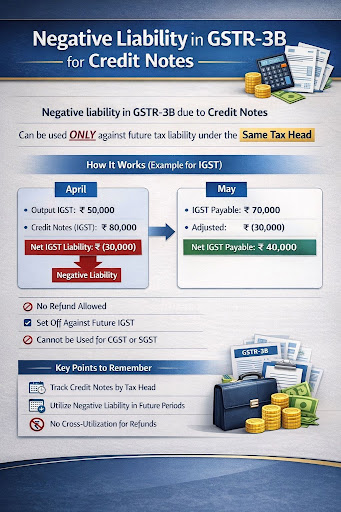
When credit notes are issued in a tax period and their value exceeds the outward tax liability of that period, the system permits reporting of negative liability in GSTR-3B.
⚠️ Key restriction:
👉 Such negative liability cannot be claimed as refund
👉 It can be adjusted only against future output tax liability
👉 Adjustment is allowed only under the same tax head (IGST / CGST / SGST)
⸻
📘 Illustration
Assume the following for IGST:
• Output IGST liability for April: ₹50,000
• Credit notes issued (IGST): ₹80,000
➡️ Net IGST liability in GSTR-3B: ₹(30,000) (negative)
🔹 This ₹30,000 will not be refunded
🔹 It will be carried forward automatically
🔹 It can be adjusted only against future IGST liability
Now, if in May, IGST payable is ₹70,000:
✔️ Adjust negative IGST of ₹30,000
✔️ Net IGST payable in May: ₹40,000
🚫 The ₹30,000 cannot be used against CGST or SGST
🚫 Refund claim is not permitted
This change brings flexibility but requires careful return planning and reconciliation.
hashtag#GSTR3B hashtag#CreditNotes hashtag#GSTReturns hashtag#CAUpdates hashtag#IndirectTax hashtag#GSTCompliance hashtag#ICAI hashtag#GSTcouncil hashtag#Consultancy hashtag#GAMP hashtag#Startupindia